Tennyson Jusu
Associate Real Estate Broker · 4 min read · 2026-10-16
Home Insurance Costs in Georgia: What Buyers and Sellers Should Know
Home insurance has become one of the most talked-about costs in real estate, and for good reason: it is now a meaningful line in every buyer's budget and every seller's disclosure conversation. Here is what Atlanta homeowners are actually paying, what is driving premiums up, and how to keep the cost manageable.
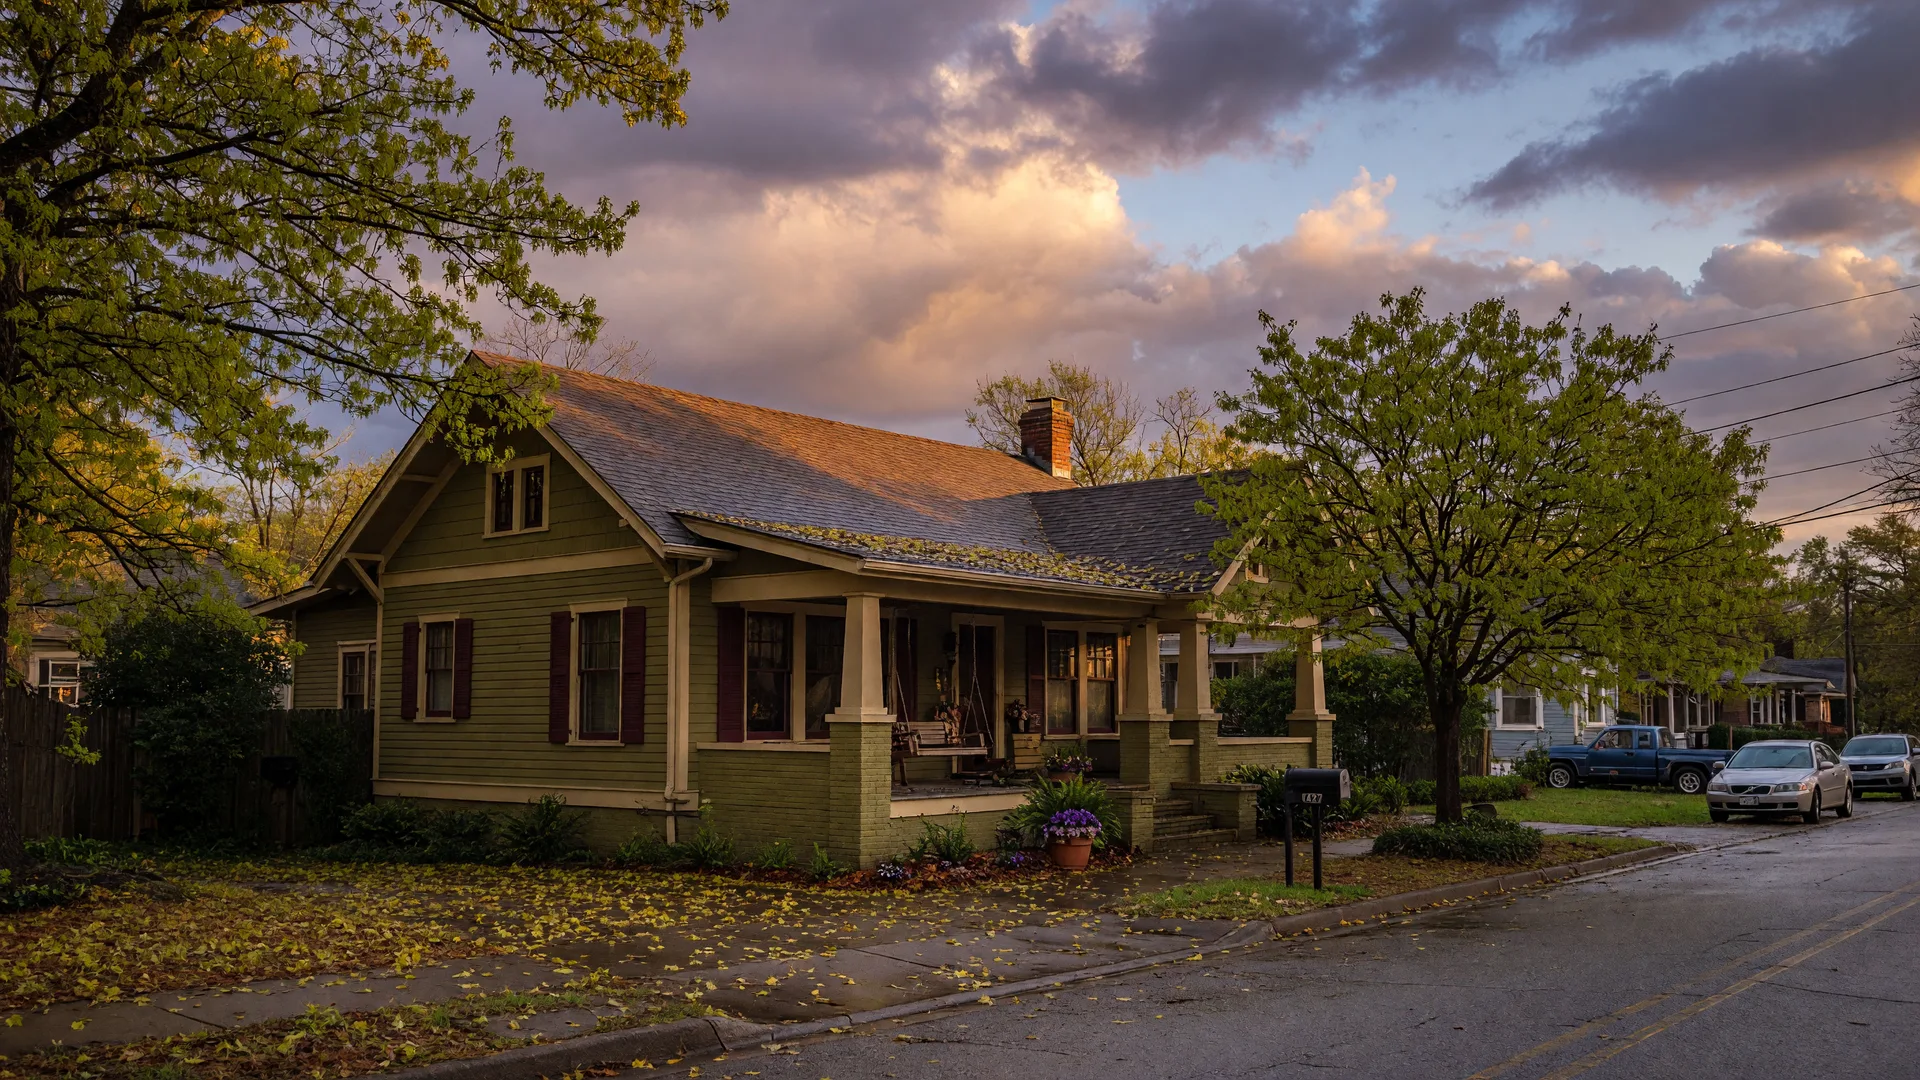
What Atlanta homeowners pay
For a home with $300,000 in dwelling coverage, published quotes for Atlanta run from roughly $1,900 to $3,200 a year depending on the insurer, the coverage, and the home itself. The national average is about $2,966 a year, and most published estimates put Georgia at or slightly below that mark. The spread between one insurer and the next is wide, which is exactly why comparison shopping pays.
Why premiums have been climbing
The big drivers are weather and rebuild costs. Atlanta ranks sixth nationally in hail claims, with the risk peaking in the spring, and severe thunderstorms and tornadoes add exposure. Many insurers now apply percentage-based wind and hail deductibles, often between 1% and 5% of the home's value, which changes your out-of-pocket cost after a storm. Meanwhile, higher construction material and labor prices have made every claim more expensive to settle, and that flows into premiums.
Roof age and credit matter more than you think
Roof age is one of the biggest single factors in your quote. Many policies now pay actual cash value on older roofs, meaning replacement cost minus depreciation, so an aging roof can raise your rate or shrink your coverage. In Georgia, credit history also factors into pricing, so buyers who are working on their credit before the mortgage application are often improving their insurance quote at the same time.
How to shop smarter
Three fast wins: compare at least three quotes with the same coverage limits, bundle home and auto policies when it makes sense, and ask about the wind and hail deductible before you commit. Also set your deductible at a level you could genuinely cover out of pocket. A few hours of shopping usually beats years of overpaying.
Buyers and sellers: plan for it
If you are buying, get a premium estimate during your home search, not after you are under contract, so insurance is part of your monthly payment math just like taxes are. If you are selling, know your own policy and any roof-related limitations before you list, so the conversation with buyers is honest from the start. Insurance is a routine cost, and it is manageable when you plan for it.
The premium is negotiable with comparison shopping, a good roof record, and a deductible you can actually handle.
Want help running the full monthly picture, including insurance, for a home you are considering? Call Tennyson at 404-343-5728.
Written by Tennyson Jusu
20+ years serving Metro Atlanta · License 245861